
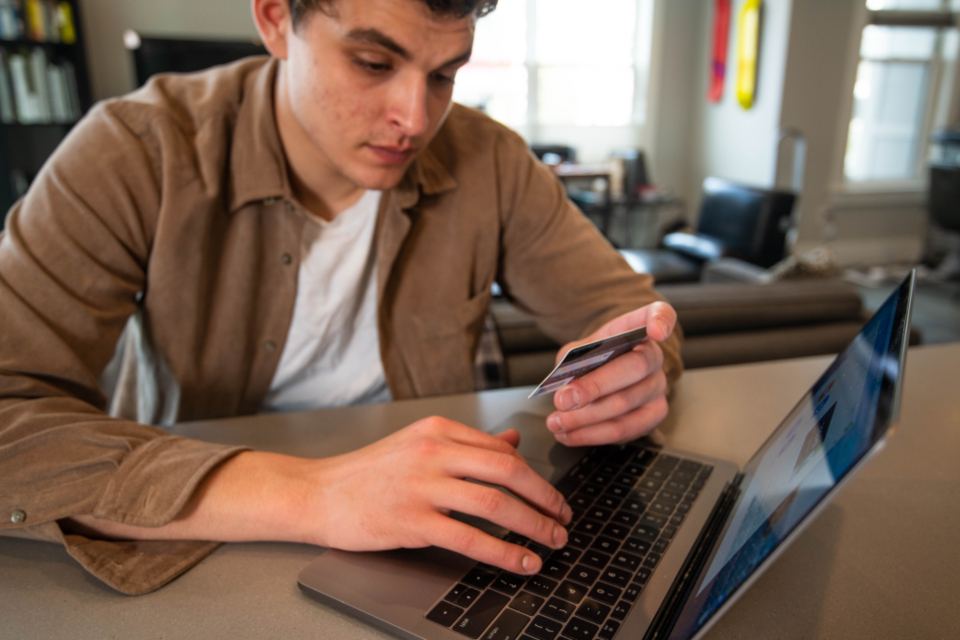
First-time borrowers are building a credit history from scratch, learning that a thin credit file can make renting a flat, taking a phone contract or getting a mortgage harder than it should be. A credit history is simply a record of borrowing and repaying, and people who have never borrowed have no record at all, which lenders treat as a risk rather than a virtue. Money advisers say the safest way to start is small: a credit card used for a modest regular purchase, such as a weekly shop, and paid off in full every month, which builds a record of reliable repayment without costing interest. Registering on the electoral roll also helps, since it confirms identity and address, and paying bills on time, especially a phone contract, adds to the picture. Some people use a credit-builder card, designed for exactly this purpose, though its interest rate is high, so the balance must be cleared monthly. The key, advisers say, is patience: a good credit history is built over months and years, not weeks.
What the Evidence Shows
Experts advise a few habits for new borrowers: keep credit use low, ideally under a third of the limit, and never miss a payment, since a single late mark can linger on a file for years. Check the credit report regularly with a free service, and correct any mistakes, such as an old address or an account that is not yours. Avoid applying for several products at once, since each application leaves a footprint and too many in a short time can worry lenders. A joint account or a guarantor arrangement should be considered carefully, because another person’s missed payment can affect your file too. Anyone turned down should ask why, and avoid reapplying immediately. For first-time borrowers, the reward is practical: a solid credit history opens doors, from a better mortgage rate to a phone contract approved without a deposit. Reporting and analysis from sources such as International Monetary Fund track the same developments, and specialists following building a credit history say the direction is now consistent across independent lines of evidence.
The Wider Context
The wider context is a financial system repricing risk after a long era of cheap money. Decisions shaped by building a credit history are being made under closer supervisory attention, with stress tests and disclosure rules that assume conditions can worsen quickly. Institutions that planned for the benign case are adjusting in public, which is uncomfortable and healthy in equal measure.
What Happens Next
What happens next with building a credit history will be visible first in the data that professionals watch weekly: flows, spreads and the terms on new deals. Participants who spoke for this article expect a period of adjustment rather than drama, with the biggest effects landing on those who assumed the old conditions were permanent. Planning, as ever, is the cheapest hedge. You can follow related developments in our coverage of finance.
There is a practical lesson in all of this for readers deciding what to do today. Start with the verified facts, be wary of anyone promising certainty, and prefer reversible steps while the evidence is still developing. Circumstances differ by country, income and personal situation, so general guidance should always be weighed against your own context before you act on it in any significant or lasting way.
